Market overview and structural significance of the Boiler, Tank, And Shipping Container Market
The Boiler, Tank, And Shipping Container Market represents a critical backbone for global industrial infrastructure and logistics, valued at $261.19 Billion in 2026. Our analysis indicates that this sector spans heavy-gauge metal storage vessels, complex heat exchangers, and ISO intermodal containers essential for cross-border maritime and overland supply chain integrity.
What are the primary drivers, restraints, and opportunities shaping the Boiler, Tank, And Shipping Container Market industry trends?
Growth is propelled by expanding seaborne trade and stricter emissions regulations by the IMO governing industrial power generation. Conversely, high raw material costs for carbon steel present recurring margin restraints. Strategic opportunities abound in lightweight composite dry storage units and high-efficiency waste heat recovery systems for heavy manufacturing facilities.
Emerging trends and technological modernization in the Boiler, Tank, And Shipping Container Market
The sector is experiencing a pronounced shift toward smart logistics integration, leveraging IoT-enabled refrigerated containers for perishable cold chains. Manufacturers are also adopting advanced automated welding to meet strict ASME pressure vessel codes, ensuring structural reliability across aggressive chemical processing environments.
How did the pandemic alter the supply chain trajectory within the Boiler, Tank, And Shipping Container Market?
The COVID-19 pandemic caused severe port bottlenecks and equipment displacement, particularly for dry storage and flat rack containers across major hubs like the Port of Shanghai. Post-pandemic recovery highlights an aggressive industry pivot toward regionalized manufacturing networks and automated yard handling equipment to mitigate future logistical shocks.
Competitive Benchmarking: Who are the dominant players in the Boiler, Tank, And Shipping Container Market?
Market concentration is high, anchored by heavyweights such as China International Marine Containers Group Ltd and Doosan Enerbility. These enterprises leverage massive production scale and localized fabrication yards to dominate large-scale power boiler and heavy-gauge metal tank procurement contracts across international energy sectors.
Executive summary of key findings for the Boiler, Tank, And Shipping Container Market market size
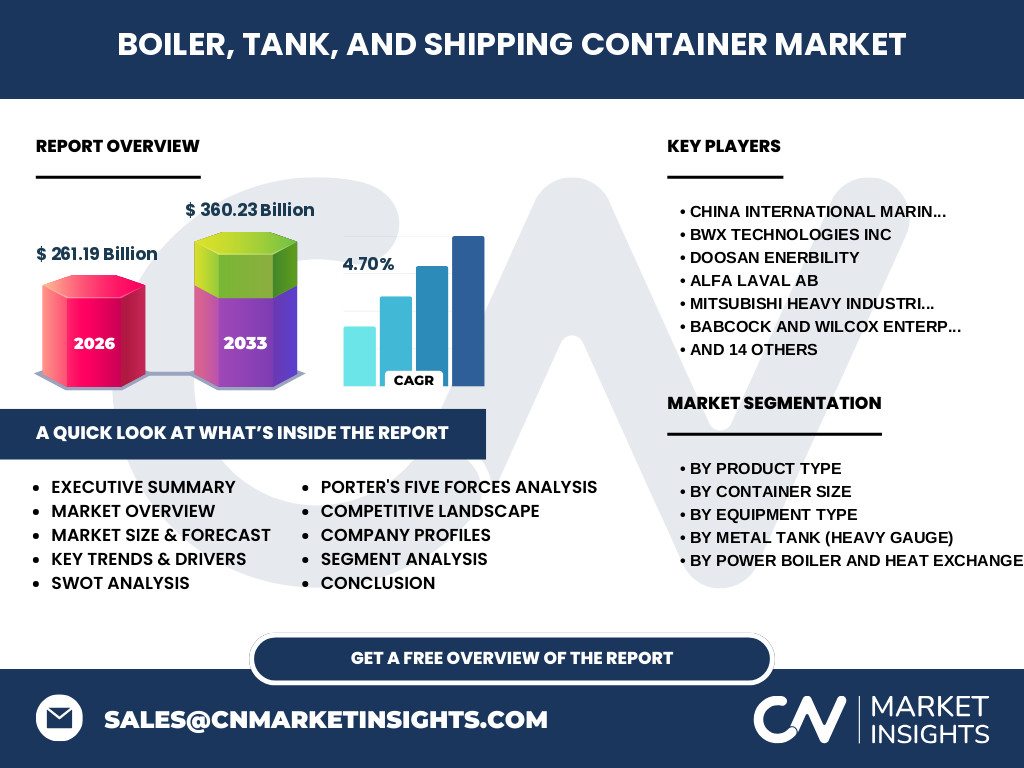
Our comprehensive research confirms a robust expansion trajectory, projecting the market to surge from $261.19 Billion in 2026 to $360.23 Billion by 2033. This growth is underpinned by a steady 4.70% CAGR, driven by power generation upgrades and expanding intermodal freight volumes worldwide.
Long-term market forecast and trajectory from 2027 to 2033
Driven by sustained investments in industrial modernization, the market will achieve a healthy 4.70% CAGR through the forecast period. We project cumulative spending to reach $360.23 Billion by 2033, heavily influenced by replacement cycles for aging industrial tanks and refrigerated intermodal fleets.
Segmentation analysis of product types, container sizes, and equipment categories
The ecosystem breaks down across equipment types like Power Boiler And Heat Exchangers and Metal Tank (Heavy Gauge), alongside intermodal units such as refrigerated and flat rack containers. Large and high cube container sizes dominate volume, while specialized pressure and storage tanks command higher margins in chemical processing plants.
Geographic distribution and regional performance across the Boiler, Tank, And Shipping Container Market
Asia-Pacific remains the primary manufacturing and consumption epicenter, supported by extensive shipbuilding and heavy industrial clusters in China, South Korea, and Japan. Meanwhile, North America and Europe exhibit steady replacement demand driven by stringent environmental compliance mandates enforced by agencies like the EPA.
In-depth regional review of manufacturing hubs and logistical bottlenecks
Regional performance is closely tied to maritime trade throughput and domestic energy policies. Asian fabrication yards maintain cost leadership, while European markets prioritize low-emission water tube boilers and advanced heat exchangers to comply with European Union decarbonization directives.
Strategic positioning of leading companies in the Boiler, Tank, And Shipping Container Market analysis
Industry leaders deploy distinct differentiation strategies. Firms like Alfa Laval AB and Mitsubishi Heavy Industries Ltd focus on high-efficiency thermal engineering, whereas BWX Technologies Inc specializes in nuclear-grade power boilers and specialized pressure containment systems requiring elite technical certifications.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to consolidated steel pricing, while buyer power is elevated among major shipping lines and utility conglomerates negotiating bulk equipment orders. Threat of substitutes is low given the specialized engineering required for high-pressure boilers and certified hazardous material storage tanks.
SWOT analysis of the industrial storage and shipping container sector
Key strengths include robust asset durability and established global logistics networks. Weaknesses center on high capital expenditure requirements. Opportunities thrive in green energy transition infrastructure, while significant threats involve volatile raw material pricing and ongoing geopolitical trade friction impacting cross-border equipment leasing.
Value chain analysis from raw material procurement to end-user deployment
The value chain originates with primary steel and alloy producers, feeding into specialized component fabricators like Thermax Ltd and Larsen and Toubro Ltd. Finished boilers, tanks, and containers flow through leasing companies and port authorities before reaching end-users in oil, gas, chemical, and maritime logistics sectors.
Investment insights and high-potential areas for capital allocation
High-potential investment pockets center on waste heat boilers, modular industrial tanks, and smart refrigerated containers equipped with real-time telematics. Capital deployed toward automated manufacturing plants will yield significant margin expansion as labor costs rise across major fabrication hubs.
Conclusion and key strategic takeaways for industry stakeholders
The Boiler, Tank, And Shipping Container Market offers compelling growth backed by a 4.70% CAGR toward $360.23 Billion. Stakeholders must prioritize technological integration, such as IoT container tracking and high-efficiency thermal equipment, to capture value in an increasingly stringent regulatory landscape.
Research methodology for baseline estimates and macroeconomic triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with c-suite executives across firms like Hyundai Heavy Industries Co Ltd and John Wood Group plc. This qualitative data is cross-referenced with trade registry statistics, customs shipping logs, and secondary macroeconomic indicators from global trade organizations.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing, segment-level performance from 2026 to 2033, and competitive mapping across twenty key market participants. Limitations exclude unregulated backyard fabricators and localized unregistered repair yards that operate outside formal customs and industrial standards frameworks.
Recent developments, strategic partnerships, and product launches in the sector
Recent market activity highlights aggressive joint ventures in low-carbon boiler technology by engineering leaders like Doosan Enerbility and IHI Corporation. Furthermore, major shipping container manufacturers have ramped up production of eco-friendly refrigerant units to align with global net-zero supply chain mandates.